


 1300 489 873


Choosing between accident-only and mid cover comes down to one question: if your dog got sick rather than hurt, could you comfortably pay the vet bill yourself? Here’s a plain-English look at what each level of cover does, and who each one suits.
The short answer
Accident-only cover helps with vet bills from sudden, unexpected injuries, like a broken leg, a deep cut or being hit by a car. Mid cover does all of that and adds illness, so it also helps with things like infections, tummy troubles and skin conditions.
Plenty of vet visits are for illness rather than accidents. So mid cover suits most dog owners, while accident-only suits tighter budgets or older dogs.
What accident-only cover looks like
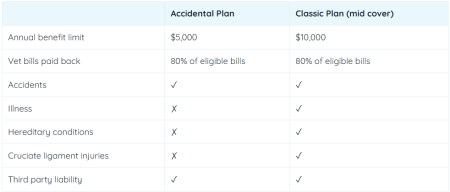
At PetsOnMe, accident-only cover is the Accidental Plan. It pays back 80% of eligible vet bills from accidents, up to $5,000 a year, and includes third party liability and prescribed medication. It’s the most affordable way to protect your dog against the big, unexpected emergencies.
What it won’t help with is illness. If your dog gets sick rather than injured, the vet bill is yours.
What mid cover adds
PetsOnMe’s mid-level option is the Classic Plan. It pays back 80% of eligible vet bills up to $10,000 a year, and covers:
- Accidents and illnesses
- Hereditary conditions
- Cruciate ligament injuries
- Third party liability and prescribed medication
Side-by-side
What the difference looks like
Picture two trips to the vet:
- Your dog cuts a paw on broken glass and needs stitches. That’s an accident, so both plans help.
- Your dog gets a stomach bug and needs tests and a night in hospital. That’s an illness, so only mid cover helps.
The gap between the two shows up the first time your dog is sick instead of hurt.
Who accident-only cover suits
- Owners on a tight budget who want a safety net for emergencies
- Older dogs, who may not qualify for illness cover
- Owners with savings set aside for illness
Who mid cover suits
- Puppies and young dogs, since getting covered early means fewer pre-existing conditions
- Breeds known for inherited health issues
- Anyone who’d struggle with a surprise illness bill in the thousands
Before you choose
Whichever level you pick, a few things apply across the board: waiting periods apply before some types of cover start, pre-existing conditions aren’t covered, and hereditary conditions have their own rules. The Product Disclosure Statement sets out the details, and it’s worth a read before you need to claim.
